


Buying a home is one of the biggest investments you can make. Whether you are a first-time homeowner or have owned a property for years, having the right home insurance in Ontario can help protect your home, belongings, and finances from unexpected events.
Home insurance can provide coverage for situations such as fire, theft, certain types of water damage, windstorms, and other covered risks. However, every policy is different, and understanding your coverage options is important before choosing an insurance plan.
In this Home Insurance Ontario Guide, we will explain what home insurance covers, what affects its cost, how to choose the right policy, and how Get Rates can help you compare insurance options.
What Is Home Insurance in Ontario?
Home insurance is a type of insurance policy designed to protect homeowners against certain unexpected losses involving their property. Depending on the policy, coverage can apply to the building itself, personal belongings, liability, and additional living expenses.
While home insurance is generally not legally required for every homeowner in Ontario, mortgage lenders commonly require homeowners to have insurance before approving a mortgage.
A suitable policy can provide financial protection if your home or belongings are damaged by a covered event.
What Does Home Insurance Cover?
Home insurance coverage varies between insurance providers and policies. However, a typical Ontario home insurance policy may include several important types of protection.
1. Dwelling Coverage
Dwelling coverage protects the physical structure of your home against covered risks. This may include the roof, walls, floors, built-in appliances, and other permanent structures.
For example, if a covered event causes significant damage to your home, dwelling coverage may help pay for eligible repair or rebuilding costs, subject to your policy limits and deductible.
2. Personal Belongings
Your home contains many valuable possessions, including furniture, clothing, electronics, appliances, and other personal items.
Personal property coverage may help replace or repair eligible belongings damaged or lost due to a covered event.
It is a good idea to keep an inventory of valuable possessions and understand the limits that apply to specific items.
3. Personal Liability Coverage
Accidents can happen on your property. Personal liability coverage can help protect you financially if you are legally responsible for causing bodily injury or property damage to another person.
For example, if a visitor is injured at your home and you are found legally responsible, liability coverage may help with eligible legal costs or damages, depending on the terms of your policy.
4. Additional Living Expenses
If your home becomes temporarily uninhabitable because of a covered loss, your policy may provide coverage for certain additional living expenses.
This can potentially help with eligible costs such as temporary accommodation and other necessary expenses while your home is being repaired.
What Is Not Covered by Home Insurance?
It is just as important to understand exclusions as it is to understand coverage.
Standard home insurance policies do not automatically cover every possible type of damage. Depending on the policy, exclusions or limitations may apply to certain events such as flooding, sewer backup, earthquakes, maintenance problems, wear and tear, or other specific risks.
Some types of coverage may be available as optional endorsements or additional protection.
Always read your policy carefully and ask your insurance provider or broker about exclusions and optional coverage
How Much Does Home Insurance Cost in Ontario?
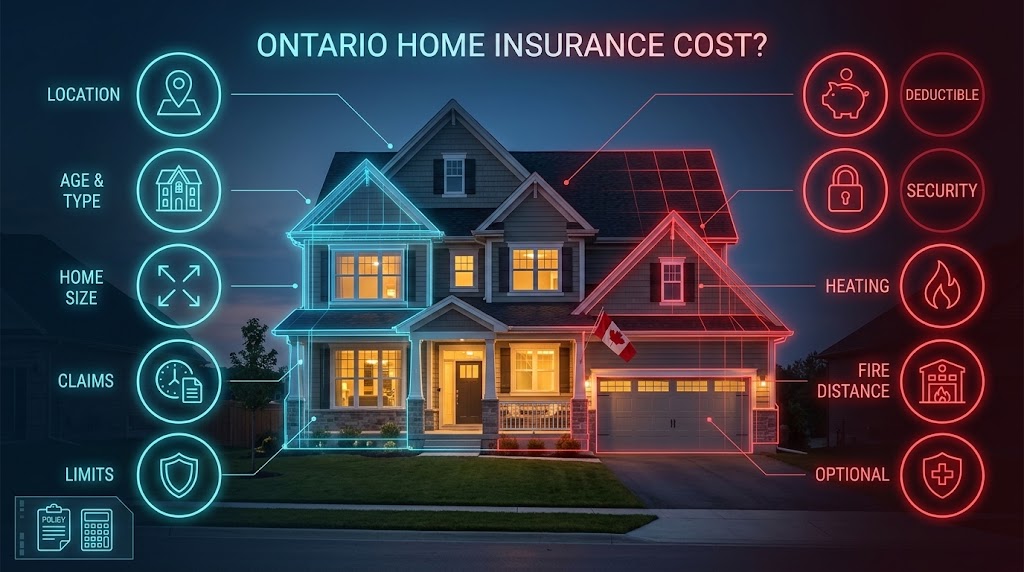
The cost of home insurance in Ontario varies from one homeowner to another. There is no single price that applies to every property.
Insurance companies may consider several factors when calculating premiums, including:
- Location of the property
- Type and age of the home
- Replacement cost of the property
- Size and construction of the home
- Claims history
- Coverage limits
- Deductible amount
- Security systems and safety features
- Heating system
- Distance from fire hydrants and fire stations
- Optional coverage and endorsements
Because different insurers use different pricing models, comparing multiple quotes can help you understand your available options.
Why Compare Home Insurance Quotes with Get Rates?
Finding the right home insurance policy can take time when you have to contact different providers individually.
Get Rates helps Canadians compare insurance options through licensed partner brokers. Its network compares quotes from more than 40 trusted insurance companies, helping homeowners explore different options based on their needs.
Get Rates focuses on making the insurance-shopping process simple, transparent, and convenient. In addition to home insurance, the platform also provides options for car and business insurance.
By comparing quotes, homeowners can better understand their choices and potentially find coverage that provides the right balance between protection and cost.
Tips to Potentially Save on Home Insurance
If you are looking for ways to reduce your home insurance premium, consider these tips:
- Compare quotes from multiple insurance providers.
- Ask about available discounts.
- Consider bundling home and auto insurance where appropriate.
- Choose a deductible you can afford.
- Install eligible security and safety devices.
- Maintain your home properly.
- Review your coverage regularly.
- Avoid unnecessary coverage gaps while looking for savings.
The goal should not simply be to find the cheapest policy. Instead, look for affordable home insurance in Ontario that provides appropriate protection for your home and belongings.
Frequently Asked Questions About Home Insurance in Ontario
Home insurance is not generally required by Ontario law for every homeowner. However, mortgage lenders commonly require homeowners to maintain insurance coverage as a condition of their mortgage.
A typical policy may cover the home structure, personal belongings, personal liability, and additional living expenses following certain covered losses. Coverage depends on the specific policy.
Amazon has several key requirements for a seller's insurance policy. The policy must:
Have a minimum limit of $1 million per occurrence and in aggregate.
Cover all products you sell on the platform.
Name "Amazon.com Services LLC and its affiliates and assignees" as an additional insured.
Be completed and signed in its entirety.
Have a deductible of no more than $10,000.
Be issued by an insurance provider with a strong financial rating (S&P A- or AM Best A- or better).
Certain types of storm-related damage may be covered, depending on your policy. Coverage can vary, so it is important to review your policy and understand its exclusions and limits.
Insurance companies can offer different prices and coverage options for similar properties. Comparing quotes can help you find an option that better matches your coverage needs and budget.
Final Thoughts
Home insurance is an important part of protecting your property and financial security. Understanding dwelling coverage, personal belongings, liability protection, deductibles, exclusions, and optional coverage can help you make a more informed decision.
Since home insurance prices and coverage options vary between homeowners and providers, comparing quotes is an important step.


