Affordable commercial liability insurance for business protection and legal coverage.
Commercial general liability insurance coverage protecting businesses from legal claims, property damage, and customer injuries.

Protect your business from third party injury and property damage claims.

Proudly Canadian, protecting Canadian businesses
5.0

Save up to 35% on your business insurance
Understanding Commercial General Liability (CGL) Insurance

Commercial General Liability (CGL) insurance is one of the most important policies for Ontario businesses. It protects against third-party claims for bodily injury, property damage, and certain personal or advertising injuries. Whether you operate a small retail shop, construction company, consulting firm, or restaurant, CGL coverage is often required by landlords, contracts, and clients before you can begin work.

What does CGL insurance cover in Ontario?

A standard Ontario CGL policy typically covers:

    • Third-party bodily injury (e.g., a customer slips and falls at your premises)

    • Third-party property damage (e.g., your employee damages a client’s property)

    • Personal and advertising injury (e.g., libel, slander, copyright infringement in advertising)

    • Legal defense costs, even if the claim is groundless

Importantly, legal fees are often covered in addition to policy limits, depending on the insurer and wording. Since legal costs in Ontario can escalate quickly, this is a critical component of the policy.

Is CGL insurance mandatory in Ontario?

CGL is not legally required by provincial law in most industries. However, it is often:

    • Required by commercial landlords

    • Required in construction contracts

    • Required by government tenders

    • Requested by corporate clients

Without CGL, many Ontario businesses simply cannot secure leases or contracts. In regulated industries (like construction or certain trades), proof of liability insurance is effectively mandatory to operate competitively.

What does CGL insurance NOT cover?

CGL policies do not cover everything. Common exclusions include:

    • Professional errors or advice (requires Errors & Omissions insurance)

    • Employee injuries (covered under WSIB in Ontario)

    • Intentional acts

    • Your own faulty workmanship (though resulting damage may be covered)

    • Cyber liability and data breaches

For example, if you are a consultant who gives incorrect advice that causes financial loss, that claim would fall under Professional Liability, not CGL.

How much CGL coverage do Ontario businesses need?

Most small businesses in Ontario carry:

    • $1 million per occurrence (minimum common standard)

    • $2 million aggregate

    • Higher limits (e.g., $5 million) for construction, manufacturing, or higher-risk industries

The appropriate limit depends on:

    • Industry risk level

    • Contractual requirements

    • Size of projects

    • Customer exposure

    • Asset protection strategy

Many commercial landlords in Ontario require at least $2 million in liability coverage.

How much does CGL insurance cost in Ontario?

Premiums vary depending on:

    • Industry type

    • Revenue

    • Payroll

    • Claims history

    • Location

    • Risk exposure

Approximate annual ranges:

    • Low-risk businesses (consulting, office-based): $400–$900

    • Retail or light service businesses: $800–$2,000

    • Contractors and higher-risk trades: $1,500–$5,000+

Pricing also depends on whether additional endorsements are needed (e.g., additional insureds, waiver of subrogation, cross-liability).

Other Business Insurance Coverage options to consider

Common claim scenarios for Commercial General Liability

Commercial General Liability (CGL) insurance protects businesses when they are held legally responsible for third-party bodily injury or property damage. In Ontario, lawsuits and legal expenses can escalate quickly, and even one incident can seriously impact cash flow and reputation. Below are three of the most common claim scenarios and how CGL coverage responds.

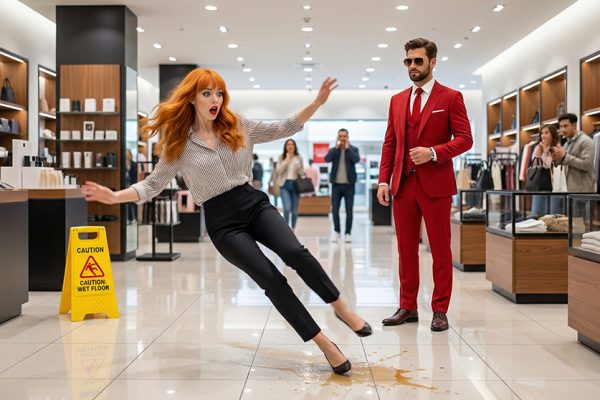
Slip-and-Fall Injury at Your Premises

Problem: A customer slips on a wet floor in your store, office, or restaurant and suffers an injury. They allege negligence and file a claim seeking compensation for medical bills, lost income, and pain and suffering. Even if the claim is exaggerated or ultimately dismissed, you are still responsible for defending yourself legally.

How Insurance Helps: CGL insurance covers third-party bodily injury claims. It pays for legal defense costs, settlements, or court-awarded damages (up to your policy limits). Without coverage, you would have to cover legal fees and potential payouts yourself, which can be financially overwhelming.

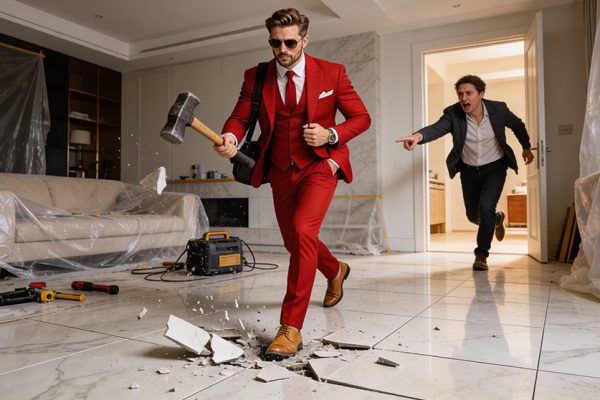
Accidental Property Damage to a Client’s Property

Problem: A contractor accidentally damages a client’s flooring during renovations, or an employee drops and breaks expensive equipment while performing work. The client demands compensation and threatens legal action to recover their losses.

How Insurance Helps: CGL covers third-party property damage resulting from your business operations. The policy can pay for repair or replacement costs, as well as legal defense if the dispute escalates. This ensures a simple accident doesn’t become a major financial setback.

Food Poisoning or Contaminated Product Claim

Problem: A customer becomes ill after eating at your restaurant or purchasing your food product. They allege food poisoning and file a claim for medical expenses, lost wages, and damages. In serious cases, multiple customers may be involved, increasing potential exposure.

How Insurance Helps: CGL policies generally cover third-party bodily injury caused by your products, including food-related illnesses. The insurance can cover legal defense costs, settlements, and judgments if your business is found liable. This protection is especially critical in the food and hospitality industry, where even one claim can severely impact operations and reputation.

Real feedback from Clients who trust us!

EXCELLENT
★★★★★
Based on reviews
Our partner brokers work for you

  • Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
  • We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
  • We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Happy clients sharing real feedback and trusted insurance service experiences
Trusted partner brokers helping clients find the best insurance coverage and rates.

Why choose GETRATES?

Experienced insurance brokers providing expert coverage advice and personalized solutions.

Experienced Brokers

Our licensed partner brokers explain coverage clearly, answer questions, and guide you on exactly what you need.

Affordable insurance coverage offering low cost protection for businesses and individuals.

Low Cost Protection

Affordable, customized business insurance that safeguards your finances and helps you recover quickly from losses.

Tailored insurance coverage designed to meet unique business and personal protection needs.

Tailored Coverage

We dive into your industry’s unique risks, craft the perfect coverage, and make sure every detail works for your business.

Affordable insurance solutions offering great coverage without high costs.
Reliable and affordable insurance coverage designed for better protection and savings.

Why great insurance doesn’t have to cost more

  • Our partner brokers work with over 40 trusted insurance providers to offer a widerange of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
  • By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
  • Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.