Cheapest Car Insurance in Ontario (2026 Guide)

0
Cheapest Car Insurance in Ontario 2026

Finding the cheapest car insurance in Ontario doesn't mean choosing the lowest price alone. The best policy offers affordable premiums while providing the coverage you need. Since Ontario has some of the highest auto insurance rates in Canada, comparing quotes and understanding what affects your premium can help you save hundreds of dollars every year.

At Get Rates, we help Ontario drivers compare personalized car insurance quotes from trusted insurance providers so they can find the right coverage at the best possible price.

Why Is Car Insurance Expensive in Ontario?

Ontario has one of the most complex auto insurance systems in Canada. Insurance premiums are influenced by several factors, including:

  • High accident claim costs
  • Vehicle theft rates
  • Repair and replacement expenses
  • Medical and accident benefit claims
  • Population density and traffic congestion

Although rates can be high, many drivers can still qualify for affordable insurance by comparing multiple quotes and taking advantage of available discounts.

Average Car Insurance Cost in Ontario

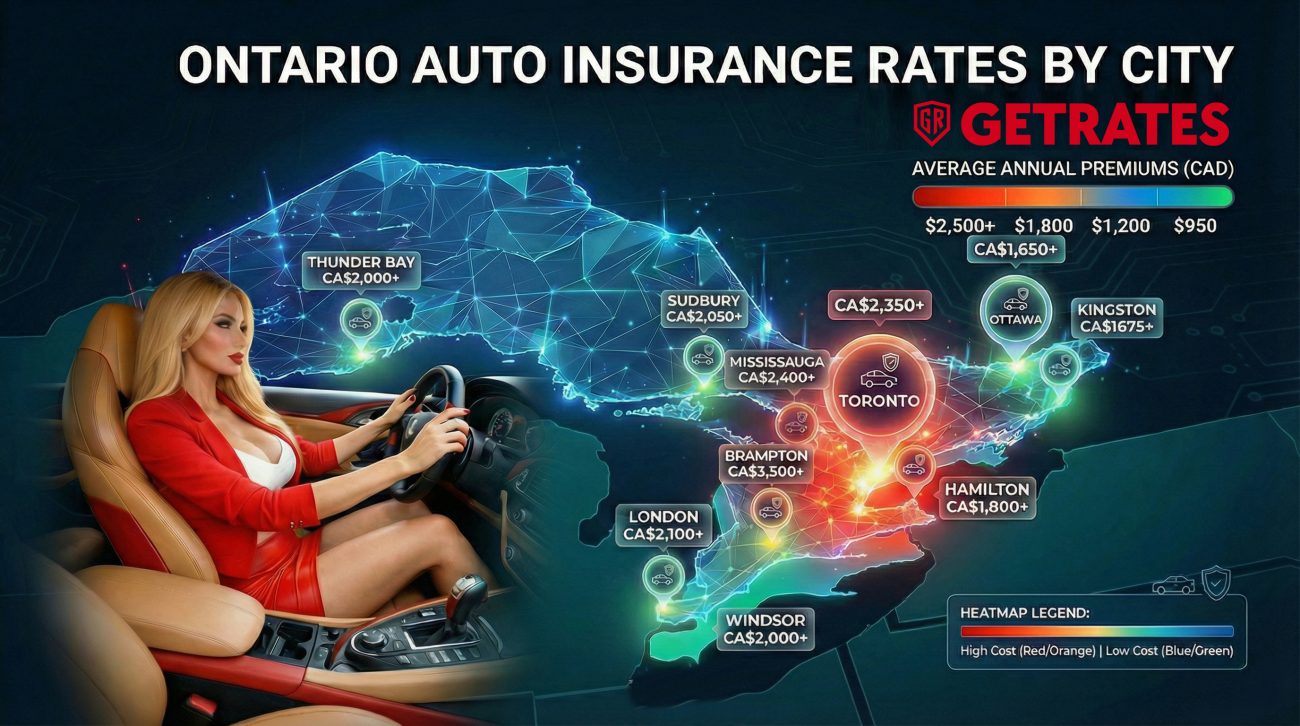
The average cost of car insurance in Ontario ranges from $1,600 to $2,200 per year, depending on your location, driving history, age, vehicle type, and coverage options.

Drivers in larger cities such as Toronto, Brampton, and Mississauga generally pay higher premiums than those living in smaller towns or rural areas

Average Car Insurance Cost in Ontario

How to Find the Cheapest Car Insurance in Ontario

Finding affordable insurance doesn't have to be difficult. Follow these proven tips to lower your premium.

1. Compare Multiple Quotes

Never buy the first policy you receive. Comparing quotes from multiple insurers helps you identify the most competitive price for the same level of coverage.

Get Rates allows you to compare personalized quotes quickly and easily from licensed insurance partners.

2. Maintain a Clean Driving Record

Safe drivers usually receive lower insurance premiums.

Avoid:

  • Speeding tickets
  • At-fault accidents
  • Distracted driving violations
  • DUI convictions

A clean driving history can significantly reduce your insurance costs over time.

3. Bundle Your Insurance Policies

Many insurers offer discounts when you combine:

Bundling policies can save you up to 20% on your premiums.

4. Choose a Higher Deductible

A higher deductible generally lowers your monthly or annual premium.

However, make sure you can comfortably afford the deductible if you need to file a claim.

5. Install Anti-Theft Devices

Vehicles equipped with approved anti-theft systems often qualify for insurance discounts because they reduce the risk of theft.

6. Drive Less

Insurance companies often reward drivers with lower annual mileage.

If you work remotely or use public transportation frequently, tell your insurer—you may qualify for additional savings.

7. Select Only the Coverage You Need

Older vehicles may not require optional coverages like collision or comprehensive insurance if the vehicle's value is low.

Review your policy regularly to avoid paying for unnecessary coverage.

Mandatory Car Insurance Coverage in Ontario

Every driver in Ontario must carry the following mandatory coverages:

  • Third-Party Liability Coverage
  • Accident Benefits Coverage
  • Direct Compensation Property Damage (where applicable)
  • Uninsured Automobile Coverage

Additional optional coverages include:

  • Collision Coverage
  • Comprehensive Coverage
  • Accident Forgiveness
  • Roadside Assistance
  • Rental Vehicle Coverage

Choosing the right combination depends on your driving habits and budget.

Who Usually Gets the Cheapest Car Insurance?

Drivers who often qualify for lower premiums include:

  • Experienced drivers with clean records
  • Drivers over 30 years old
  • Low-mileage drivers
  • Owners of vehicles with strong safety ratings
  • Drivers who bundle insurance policies
  • Individuals with no previous claims

Mistakes That Can Increase Your Insurance Premium

Avoid these common mistakes:

  • Not comparing quotes
  • Filing multiple small claims
  • Allowing your policy to lapse
  • Choosing unnecessary coverage
  • Providing inaccurate information
  • Ignoring available discounts

Reviewing your policy annually helps ensure you're getting the best possible rate.

Factors That Affect Car Insurance Rates

Factors that affect car insurance rates in Ontario

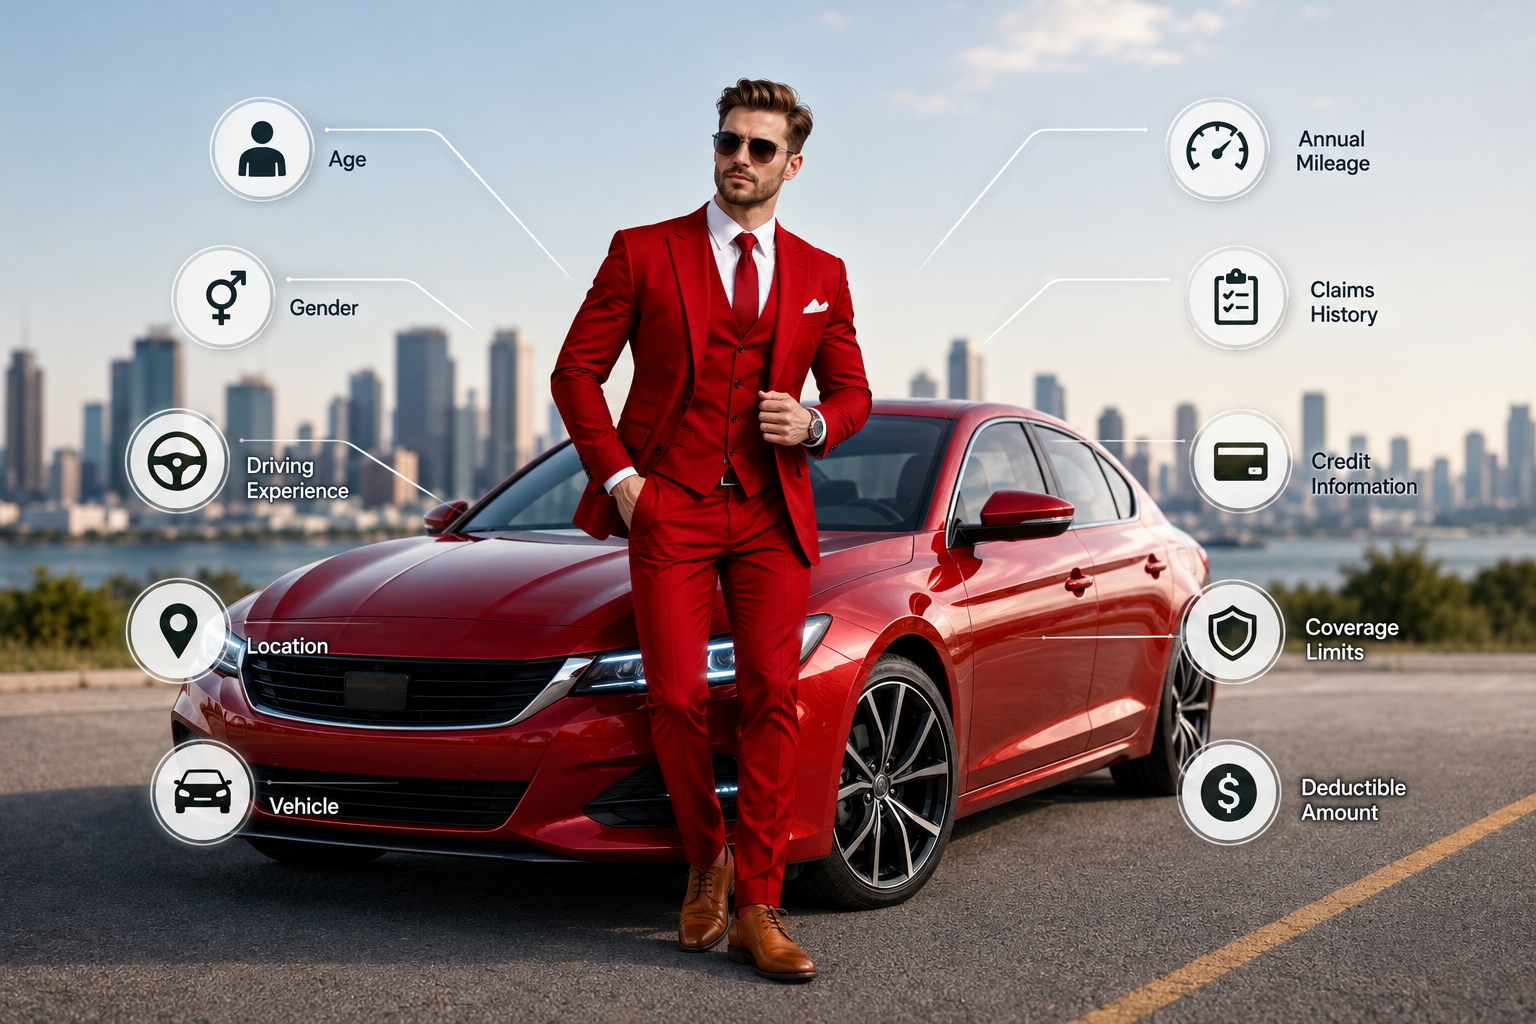
Insurance companies calculate premiums using several risk factors, including:

  • Age
  • Gender
  • Driving experience
  • Postal code
  • Vehicle make and model
  • Annual mileage
  • Claims history
  • Credit information (where permitted)
  • Coverage limits
  • Deductible amount

Improving these factors where possible can help reduce your insurance costs.

Why Compare Quotes with Get Rates?

Shopping around is one of the easiest ways to save money.

With Get Rates, you can:

Whether you're purchasing insurance for the first time or renewing your policy, comparing multiple quotes can help you find the coverage that fits both your needs and your budget.

Frequently Asked Questions (FAQs)

What is the cheapest car insurance company in Ontario?

There isn't a single company that's the cheapest for everyone. Insurance rates vary based on your age, driving history, location, vehicle, and coverage needs. Comparing quotes is the best way to find the lowest price.

How can I lower my car insurance in Ontario?

You can reduce your premium by comparing quotes, maintaining a clean driving record, bundling policies, increasing your deductible, driving fewer kilometres, and taking advantage of available discounts.

What is the average cost of car insurance in Ontario?

Most Ontario drivers pay between $1,600 and $2,200 per year, although your actual premium may be higher or lower depending on your personal profile.

Is car insurance mandatory in Ontario?

Yes. Every driver must have mandatory auto insurance, including Third-Party Liability, Accident Benefits, Uninsured Automobile Coverage, and other required protections under Ontario law.

How often should I compare car insurance quotes?

It's recommended to compare quotes at least once a year or whenever your policy is up for renewal, your driving record changes, or you purchase a new vehicle.

Final Thoughts

Finding the cheapest car insurance in Ontario is about more than choosing the lowest premium. The right policy balances affordability, protection, and excellent customer service.

By comparing quotes, maintaining a clean driving record, selecting appropriate coverage, and taking advantage of discounts, you can reduce your insurance costs while staying fully protected.

Before renewing your current policy, compare your options through Get Rates and see how much you could save.

Leave a Reply

Your email address will not be published. Required fields are marked *