Professional liability insurance protection for accounting practices and financial professionals

Safeguard your Accounting Practice with professional liability insurance.

Proudly Canadian, protecting Canadian businesses

Save up to 35% on your business insurance

Grab your business insurance quote in moments!

Understanding Insurance for Accounting Professionals

Accounting professionals face unique risks — from calculation errors and missed deadlines to data breaches and client disputes. Even small mistakes can lead to costly legal claims, reputational damage, or regulatory issues. Having the right insurance coverage helps protect your business, finances, and professional credibility while allowing you to focus on serving clients with confidence.

Below are five essential questions accountants commonly ask about insurance coverage, along with detailed answers to help clarify what protection you may need.

What is professional liability insurance for accountants?

Professional liability insurance (also called errors and omissions or E&O insurance) protects accountants against claims alleging negligence, mistakes, omissions, or failure to deliver promised services. For example, if a client claims you miscalculated taxes, missed a filing deadline, or provided incorrect financial advice that caused them financial loss, this policy can help cover legal defense costs, settlements, or judgments.

Even if a claim is unfounded, legal defense alone can be expensive. Professional liability insurance ensures you’re not paying those costs out of pocket. For accountants, this is often considered the most essential form of coverage because it directly protects against the primary risks associated with professional services.

Is general liability insurance necessary for accountants?

Yes. While professional liability covers service-related errors, general liability insurance protects against third-party bodily injury, property damage, and certain advertising-related claims. For example, if a client slips and falls in your office or you accidentally damage client property during an onsite visit, general liability insurance can cover medical expenses, repair costs, and legal fees.

Even home-based or virtual accountants can benefit from this coverage. Accidents can happen in any workspace, and many commercial leases require proof of general liability insurance. It adds an important layer of protection beyond professional mistakes.

Do accountants need cyber liability insurance?

In today’s digital environment, cyber liability insurance is increasingly important. Accountants handle sensitive financial data, including social insurance numbers, banking details, payroll records, and tax information. If your systems are hacked, data is breached, or ransomware locks your files, cyber insurance can help cover notification costs, forensic investigations, legal expenses, public relations efforts, and even extortion payments.

Data breaches can be costly and damaging to client trust. Cyber liability insurance helps mitigate financial fallout and supports business continuity in the event of a digital incident.

How much professional liability coverage should an accountant carry?

The right coverage limit depends on factors such as the size of your practice, the services you provide, annual revenue, and the type of clients you serve. For example, accountants working with large corporate clients or offering complex tax or advisory services may require higher limits than those handling basic bookkeeping for small businesses.

Common policy limits start at $1 million per claim, but higher limits may be appropriate depending on exposure. It’s important to assess your risk realistically — one significant claim could exceed minimum coverage limits if not properly structured.

Is insurance required by law for accountants?

Insurance requirements vary by province, state, and professional designation. In some jurisdictions, certain licensed accountants or firms must carry professional liability insurance to maintain good standing with regulatory bodies. Even when not legally required, many clients, lenders, and business partners expect proof of insurance before signing contracts.

Beyond compliance, insurance demonstrates professionalism and financial responsibility. It reassures clients that you are prepared to address potential errors or unexpected situations responsibly.

Accounting Businesses That Typically Require Insurance Coverage

Our partner brokers work for you

  • Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
  • We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
  • We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Happy clients sharing real feedback and trusted insurance service experiences
Trusted partner brokers helping clients find the best insurance coverage and rates.

Why choose GETRATES?

Experienced insurance brokers providing expert coverage advice and personalized solutions.

Experienced Brokers

Our licensed partner brokers explain coverage clearly, answer questions, and guide you on exactly what you need.

Affordable insurance coverage offering low cost protection for businesses and individuals.

Low Cost Protection

Affordable, customized business insurance that safeguards your finances and helps you recover quickly from losses.

Tailored insurance coverage designed to meet unique business and personal protection needs.

Tailored Coverage

We dive into your industry’s unique risks, craft the perfect coverage, and make sure every detail works for your business.

Affordable insurance solutions offering great coverage without high costs.
Reliable and affordable insurance coverage designed for better protection and savings.

Why great insurance doesn’t have to cost more

  • Our partner brokers work with over 40 trusted insurance providers to offer a wide range of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
  • By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
  • Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.

Why Insurance Matters: Common Claims Accountants Face

Accounting professionals work in a detail-driven environment where even small errors can have significant financial consequences. From filing deadlines to data security, the risks are real and increasingly complex. Insurance provides critical financial protection when mistakes, accidents, or cyber incidents lead to costly claims. Below are three of the most common claim scenarios accountants encounter and how insurance responds.

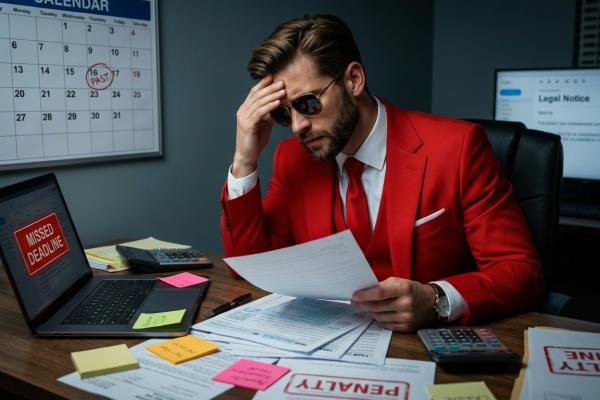
Tax Filing Error or Missed Deadline

Problem: An accountant misses a tax filing deadline or makes a calculation error that results in penalties, interest charges, or financial loss for a client. The client may allege negligence and pursue legal action to recover their losses. Even if the mistake was minor or partially caused by incomplete client information, defending the claim can be expensive and time-consuming.

How Insurance Helps: Professional liability (E&O) insurance helps cover legal defense costs, settlements, or court-awarded damages related to service errors or omissions. This ensures the accountant does not have to pay substantial legal expenses out of pocket and can continue operating the business while the matter is resolved.

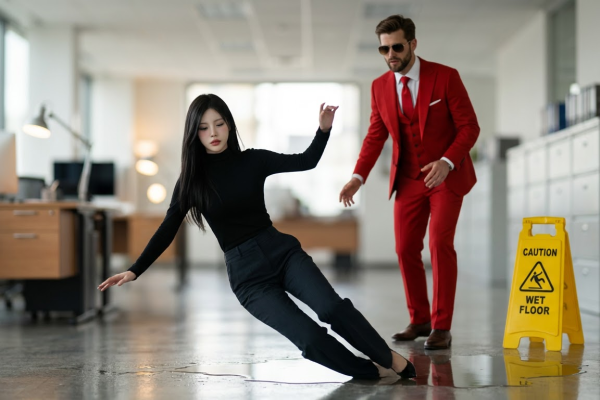
Client Slip-and-Fall or Property Damage

Problem: A client visiting the accountant’s office slips on a wet floor or trips over loose carpeting, resulting in injury. Alternatively, an accountant working at a client’s location accidentally damages equipment or property. The injured party may seek compensation for medical expenses or repair costs.

How Insurance Helps: General liability insurance covers third-party bodily injury and property damage claims. It can pay for medical bills, legal defense costs, settlements, and repair expenses. This protects the accountant’s business assets from being used to cover unexpected accidents unrelated to professional advice.

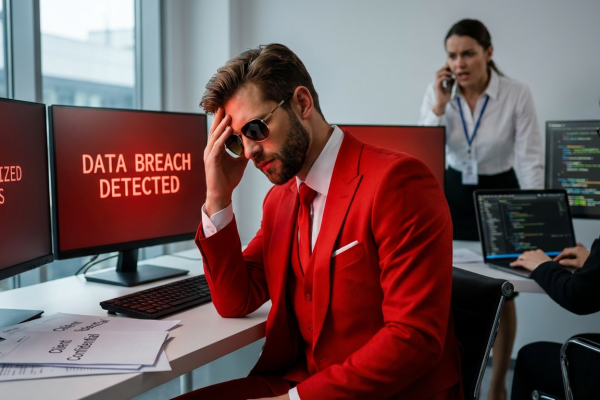
Data Breach or Cyberattack

Problem: An accounting firm’s systems are hacked, exposing sensitive client information such as tax records, banking details, or payroll data. The firm may be legally required to notify affected clients, hire cybersecurity experts, and manage reputational damage. Clients could also file lawsuits claiming failure to safeguard their confidential information.

How Insurance Helps: Cyber liability insurance can cover breach notification costs, forensic investigations, legal fees, credit monitoring services for affected clients, public relations support, and certain regulatory fines where permitted. This coverage helps the firm recover financially and maintain client trust after a cyber incident.