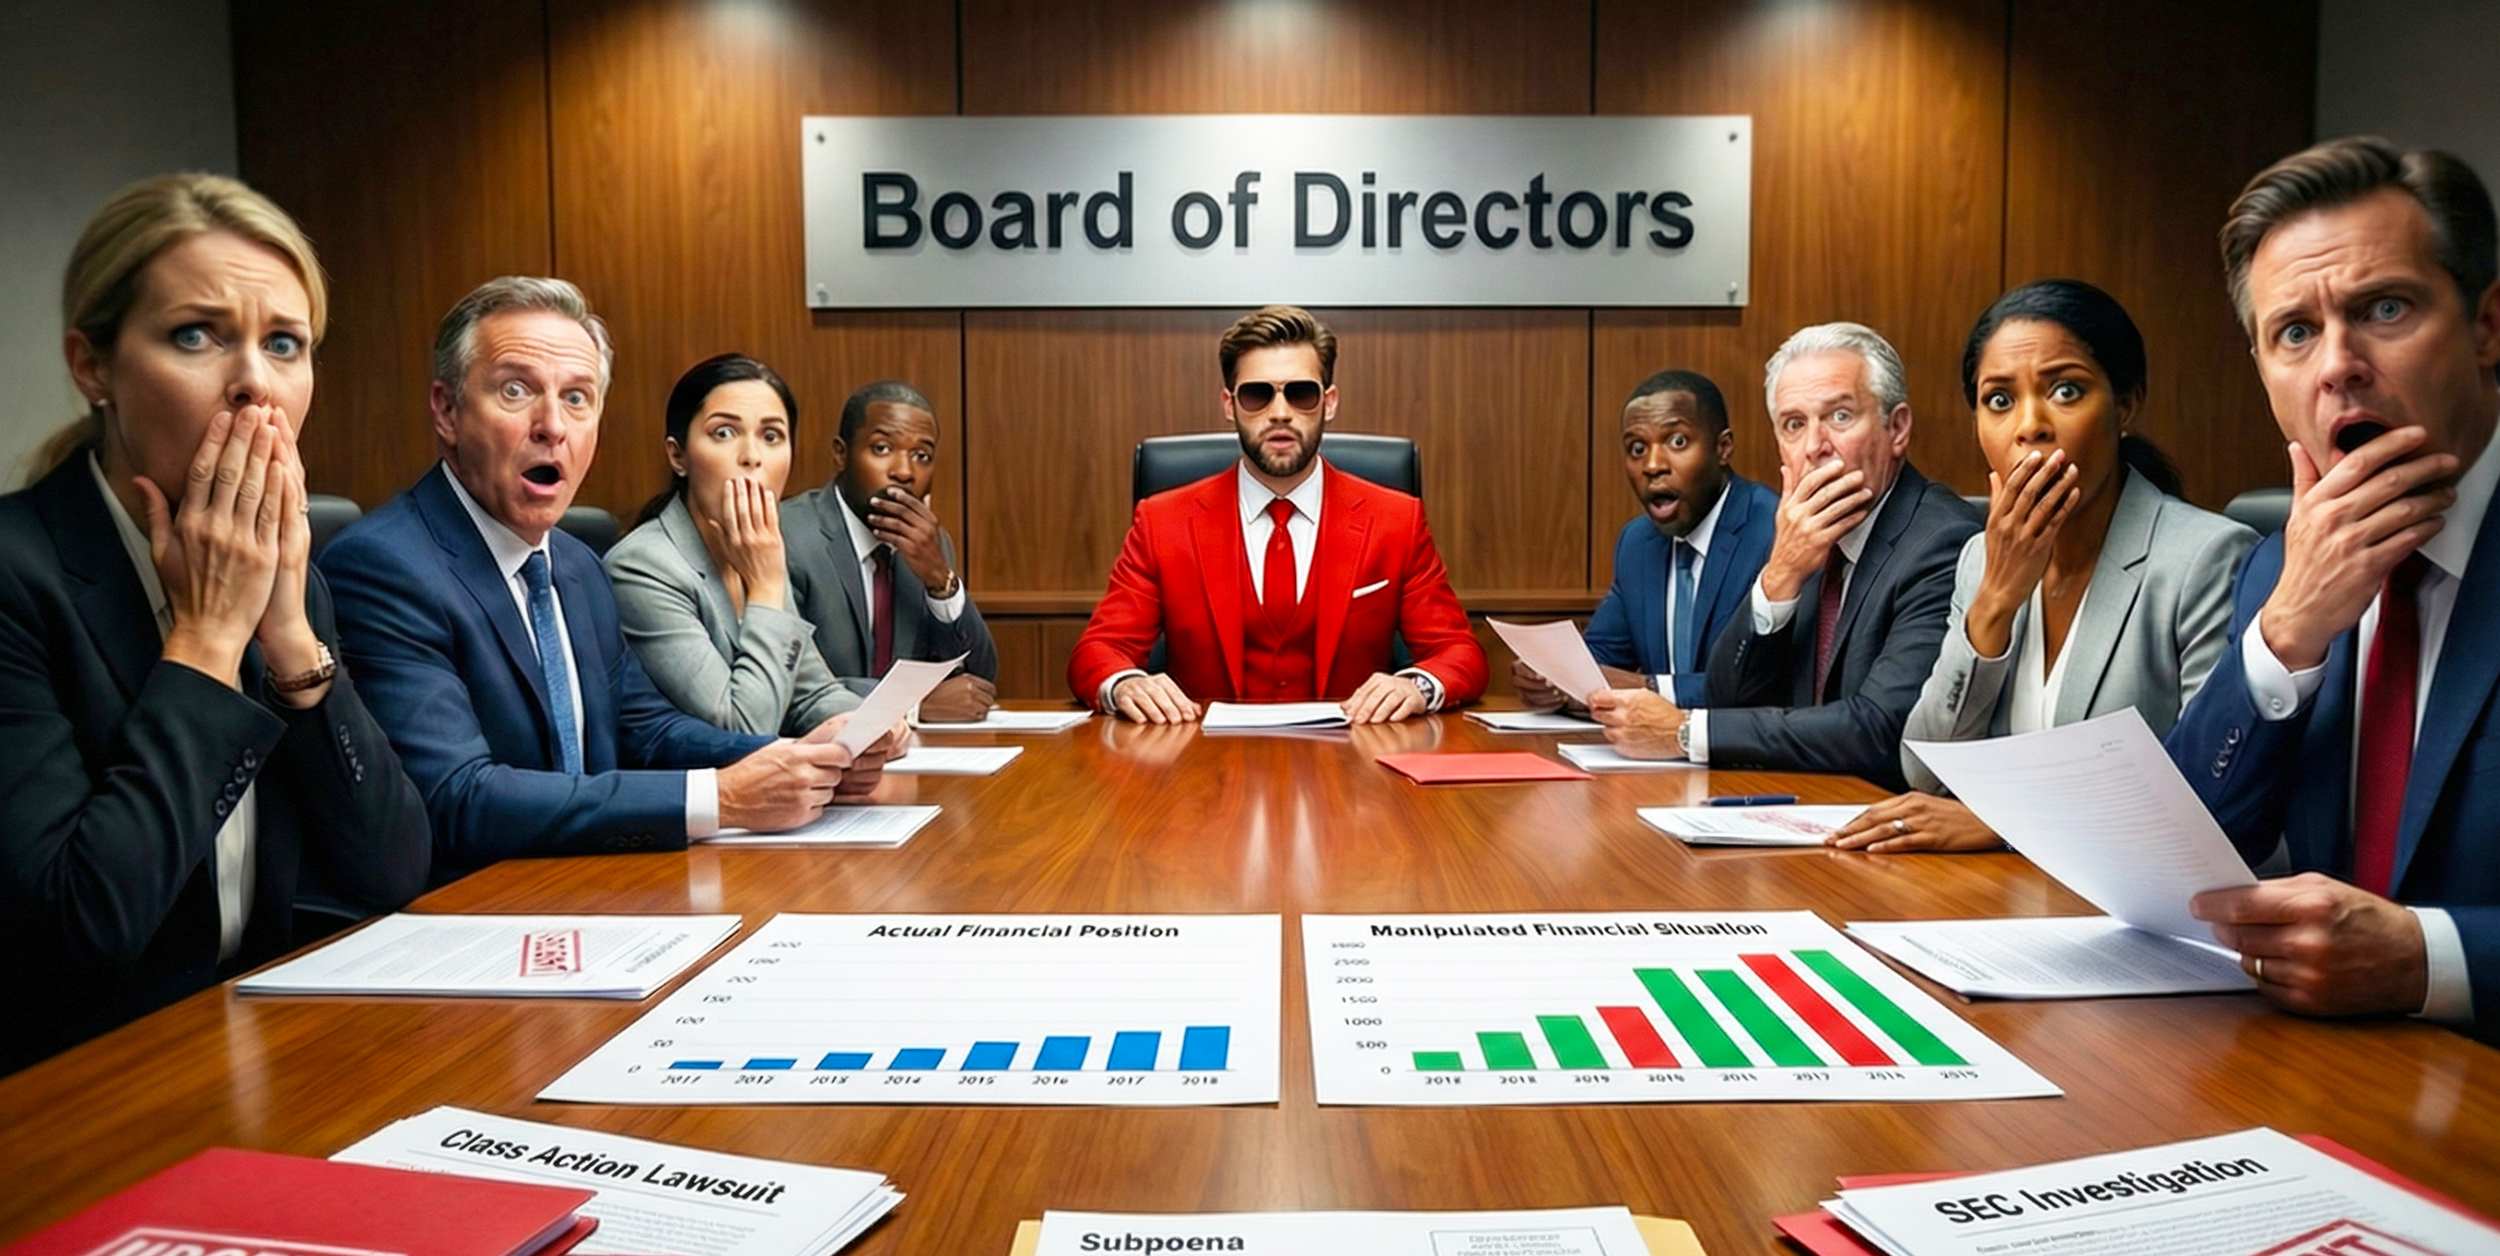
Board members face personal liability. Directors and Officers Insurance protects them.
Proudly Canadian, protecting Canadian businesses
5.0
Save up to 35% on your business insurance
Understanding Directors & Officers (D&O) Insurance
Directors and Officers Insurance protects board members, executives, and senior leaders from personal financial loss if they are sued for decisions made while managing an organization. Lawsuits can come from shareholders, investors, employees, regulators, creditors, or even competitors. Even unfounded allegations can result in significant legal expenses. D&O coverage helps pay for defense costs, settlements, and judgments—shielding personal assets and supporting organizational stability.
D&O Insurance covers claims alleging wrongful acts in managing or governing an organization. This can include breach of fiduciary duty, misrepresentation, mismanagement, regulatory investigations, failure to comply with corporate laws, or misleading financial reporting.
The policy typically pays for legal defense costs, settlements, and court-ordered judgments. Coverage may apply to individual directors and officers (Side A), the organization itself (Side B reimbursement), and in some cases the entity directly (Side C entity coverage), depending on the policy structure.
Any organization with a board of directors or executive leadership should consider D&O coverage. This includes public companies, private corporations, startups, non-profits, and even family-owned businesses with formal governance structures.
Board members can be personally named in lawsuits regardless of company size. In many cases, experienced executives will not join a board without D&O protection in place because their personal assets could otherwise be at risk.
Common D&O claims include shareholder disputes, allegations of financial misrepresentation, employment-related claims against leadership, bankruptcy-related suits, and regulatory investigations. For private companies, disputes among shareholders or investors are especially common.
Even when claims are ultimately dismissed, defense costs can escalate quickly. Complex corporate litigation often requires specialized legal counsel, forensic accounting experts, and extended court proceedings.
D&O policies generally exclude intentional fraud, criminal acts, illegal profits, and prior known claims. Coverage may also exclude bodily injury and property damage, which are typically handled under other policies such as General Liability.
It’s important to review policy wording carefully, including exclusions and conditions, to understand how coverage applies to your organization’s specific risk profile.
Coverage limits vary based on company size, industry, revenue, investor involvement, and regulatory exposure. Smaller private companies may carry limits starting at $1 million, while larger organizations may require significantly higher limits.
When evaluating limits, consider potential defense costs alone—complex cases can run into hundreds of thousands or millions of dollars. Many companies also review contractual obligations with investors or lenders who may require specific D&O limits.
Other Business Insurance Coverage options to consider
- Commercial General Liability Insurance
- Errors and Omissions Insurance
- Professional Liability Insurance
- Directors and Officers Insurance
- Cyber Liability Insurance
- Business Liability Insurance
- Equipment Breakdown Insurance
- Builders Risk Insurance
- Commercial Property Insurance
- Commercial Auto Insurance
- Commercial Crime Insurance
- Commercial Truck Insurance
- Legal Expense Insurance
- Media Liability Insurance
- Pollution Liability Insurance
- Product Recall Insurance
- Tools and Equipment Insurance
- Vacant Property Insurance
- Business Contents Insurance
- Employers Liability Insurance
- Cargo Insurance
- Special Event Insurance
- Malpractice Insurance
- Fleet Insurance
- Commercial Tenant Insurance
- Liquor Liability Insurance
- Cyber Crime Insurance
Common claim scenarios for Directors & Officers (D&O) Insurance
Directors and Officers (D&O) Insurance protects board members and executives when management decisions trigger legal action. Claims often arise from financial performance, governance disputes, or regulatory scrutiny. Even when leaders act in good faith, allegations alone can result in substantial defense costs and personal exposure.
Shareholder or Investor Lawsuit
Problem: Shareholders or investors allege misrepresentation, poor financial disclosure, or breach of fiduciary duty after company losses or a drop in valuation. They may claim leadership failed to disclose risks, overstated projections, or mismanaged company funds.
How Insurance Helps: D&O Insurance covers legal defense costs, forensic accounting, expert witnesses, and potential settlements. Complex shareholder litigation can easily cost $250,000 to $1 million+ in defense alone. Settlements may range from several hundred thousand dollars to multiple millions depending on company size and financial impact. With typical policy limits starting at $1 million and often much higher, D&O coverage helps protect both the organization and individual executives from devastating financial consequences
Regulatory Investigation or Compliance Allegation
Problem: A regulatory body investigates the company for alleged non-compliance, reporting failures, or governance issues. Directors and officers may be personally named in the investigation, even if no wrongdoing is ultimately proven.
How Insurance Helps: D&O Insurance can cover legal representation during investigations, document production costs, and settlement negotiations. Regulatory defense expenses alone can exceed $100,000–$500,000 depending on the complexity and duration of the investigation. Coverage ensures leadership can respond properly without personally funding a lengthy legal defense
Employment-Related Management Claims
Problem: Senior leadership is accused of wrongful termination, discrimination, or mismanagement decisions impacting employees. While Employment Practices Liability Insurance (EPLI) often responds first, executives may still be individually named in lawsuits alleging governance failures.
How Insurance Helps: D&O coverage can provide protection when executives are personally named in management-related claims tied to oversight decisions. It helps fund defense costs and protects personal assets, ensuring that leadership is not individually exposed due to company-level disputes.
Real feedback from Clients who trust us!
Our partner brokers work for you
- Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
- We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
- We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Why choose GETRATES?
Why great insurance doesn’t have to cost more
- Our partner brokers work with over 40 trusted insurance providers to offer a widerange of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
- By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
- Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.