Protect your business from negligence claims with Professional Liability Insurance.
Proudly Canadian, protecting Canadian businesses
5.0
Save up to 35% on your business insurance
Understanding Professional Liability Insurance
Professional Liability Insurance—also known as Errors & Omissions (E&O) Insurance—protects businesses and professionals when a client claims they made a mistake, were negligent, or failed to deliver services as promised. Even if a claim is unfounded, legal defense costs alone can be financially damaging. This coverage helps pay for legal fees, settlements, and judgments, protecting both reputation and financial stability.
Professional Liability Insurance covers claims related to errors, omissions, negligence, misrepresentation, inaccurate advice, or failure to meet contractual obligations. Unlike General Liability Insurance, which covers bodily injury or property damage, this policy focuses on financial loss caused by professional services.
For example, a consultant giving incorrect advice, a realtor failing to disclose material property information, or a designer missing a deadline could all trigger a claim. The policy typically pays for legal defense costs, court fees, settlements, and judgments—even if the claim is groundless.
Any professional who provides advice, expertise, or services for a fee should consider this coverage. This includes real estate agents, consultants, accountants, lawyers, insurance brokers, IT professionals, architects, marketing agencies, and many others.
Even highly experienced professionals can face allegations. Clients may claim financial loss due to dissatisfaction, misunderstanding, or unexpected outcomes. In today’s litigious environment, one lawsuit can significantly impact a small business.
While policies vary, most do not cover intentional wrongdoing, criminal acts, bodily injury, property damage, or employee-related disputes (which are typically covered under other policies like General Liability or Employment Practices Liability).
Additionally, prior known claims or incidents that occurred before the policy’s retroactive date are usually excluded. It’s important to review policy wording carefully to understand coverage limitations and exclusions.
Most Professional Liability policies operate on a claims-made basis. This means the policy must be active both when the alleged incident occurred (after the retroactive date) and when the claim is filed.
If coverage lapses or is cancelled, future claims for past work may not be covered unless “tail coverage” (extended reporting period) is purchased. Maintaining continuous coverage is critical to ensure long-term protection.
Coverage limits depend on your industry, contract requirements, revenue size, and risk exposure. Many professionals carry limits such as $1 million per claim and $2 million aggregate, but higher limits may be necessary for larger contracts or higher-risk industries.
A risk assessment considering your client base, average project size, and potential financial exposure will help determine appropriate limits. It’s also important to factor in defense costs, which can accumulate quickly.
Other Business Insurance Coverage options to consider
- Commercial General Liability Insurance
- Errors and Omissions Insurance
- Professional Liability Insurance
- Directors and Officers Insurance
- Cyber Liability Insurance
- Business Liability Insurance
- Equipment Breakdown Insurance
- Builders Risk Insurance
- Commercial Property Insurance
- Commercial Auto Insurance
- Commercial Crime Insurance
- Commercial Truck Insurance
- Legal Expense Insurance
- Media Liability Insurance
- Pollution Liability Insurance
- Product Recall Insurance
- Tools and Equipment Insurance
- Vacant Property Insurance
- Business Contents Insurance
- Employers Liability Insurance
- Cargo Insurance
- Special Event Insurance
- Malpractice Insurance
- Fleet Insurance
- Commercial Tenant Insurance
- Liquor Liability Insurance
- Cyber Crime Insurance
Common claim scenarios for Professional Liability Insurance )
Professional Liability Insurance exists for one core reason: even experienced, ethical professionals can face claims of negligence, misrepresentation, or failure to deliver services as promised. Many claims arise from misunderstandings, missed details, or unmet expectations—not intentional wrongdoing. Below are three of the most common claim scenarios and how this coverage protects your business.
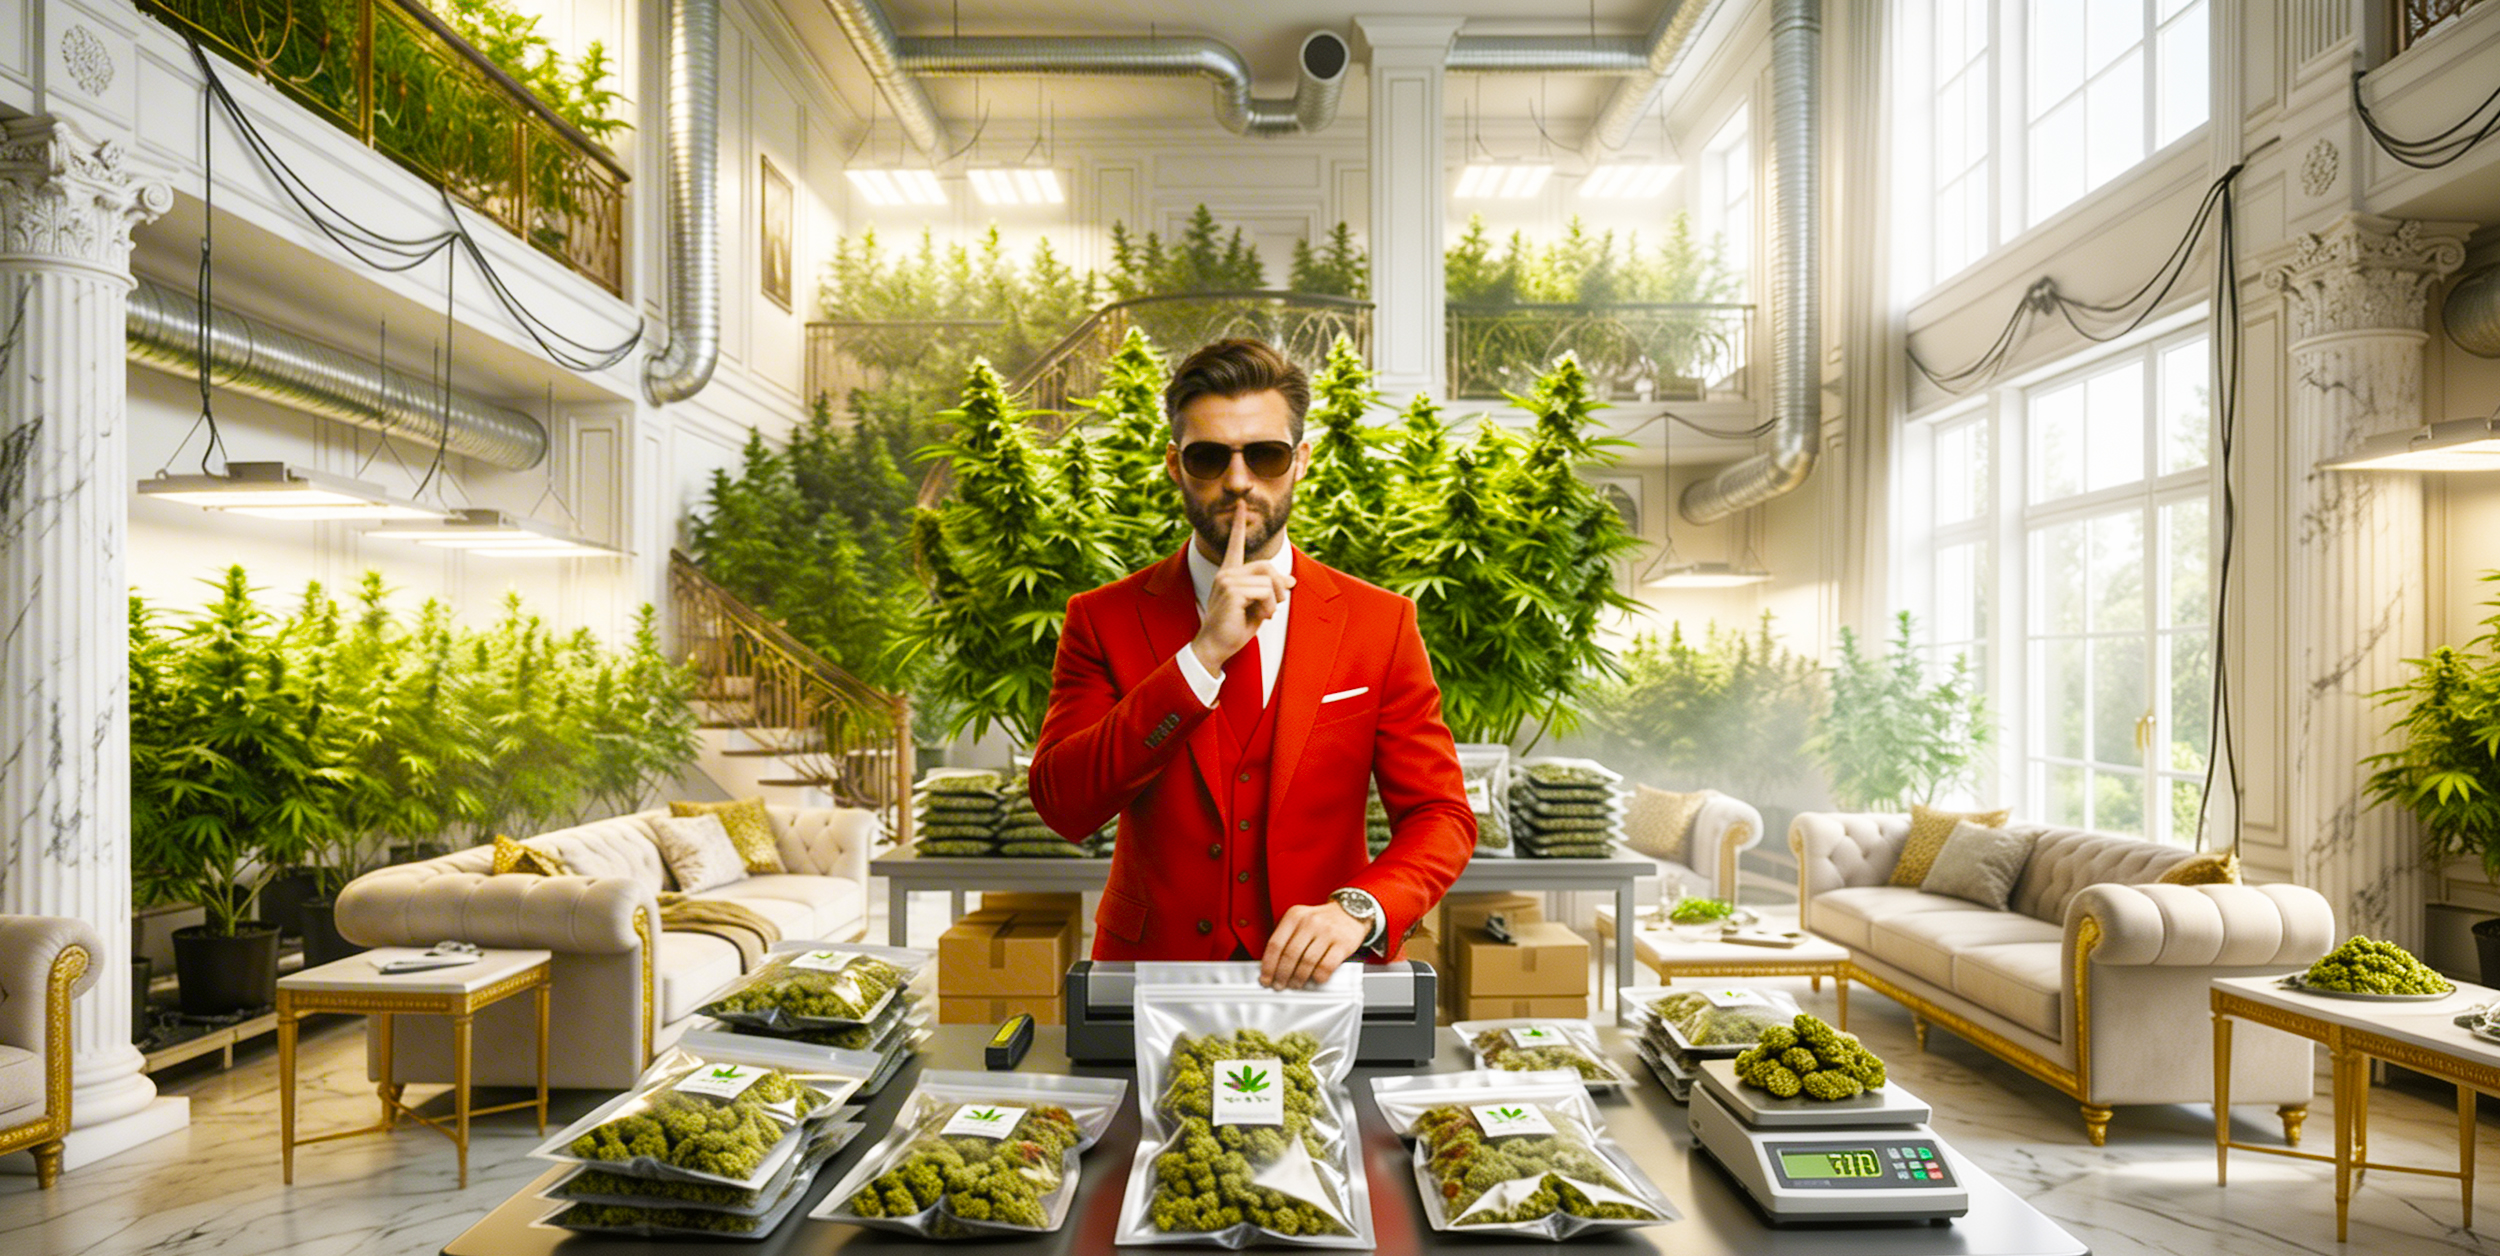
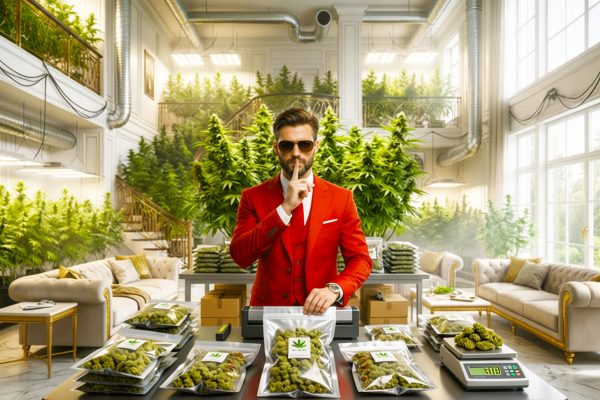
Undisclosed Marijuana Grow Operation
Problem: A realtor sells a home without disclosing its past as a marijuana grow operation. After closing, the buyer finds hidden mold, electrical alterations, and moisture damage. Repair costs surge, leading to a lawsuit for negligent misrepresentation and failure to disclose, including claims for repairs, lost value, and legal fees.
How Insurance Helps: Professional Liability (E&O) Insurance covers legal defense costs—often $25,000–$75,000 or more—and potential settlements that can reach $100,000–$300,000+, depending on damages. With limits commonly at $1 million per claim, the policy helps cover defense, expert costs, and settlements, protecting the realtor’s finances and reputation.
Financial Loss from Professional Advice
Problem: A client follows your professional advice—whether financial, technical, consulting, or strategic—and the outcome leads to unexpected financial loss. Even if the advice was reasonable at the time, the client may claim it fell below professional standards.
How Insurance Helps: Professional Liability Insurance responds to claims that your advice caused economic harm. It covers defense expenses and negotiated settlements, helping ensure one dissatisfied client does not jeopardize your long-term financial stability.
Missed Deadline or Administrative Error
Problem: A professional misses a key deadline—such as a filing date, contract condition, regulatory submission, or closing requirement. The client experiences financial loss and files a negligence claim. Even an unintentional clerical error can result in lost deals, penalties, or breach-of-contract allegations.
How Insurance Helps: Professional Liability Insurance covers legal defense costs, which can easily range from $15,000 to $50,000 or more depending on complexity. If the matter settles, payouts could range from $25,000 to several hundred thousand dollars depending on the client’s financial loss. The policy responds up to the coverage limit (commonly $1M per claim), helping protect your operating capital and business continuity
Real feedback from Clients who trust us!
Our partner brokers work for you
- Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
- We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
- We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Why choose GETRATES?
Why great insurance doesn’t have to cost more
- Our partner brokers work with over 40 trusted insurance providers to offer a widerange of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
- By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
- Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.