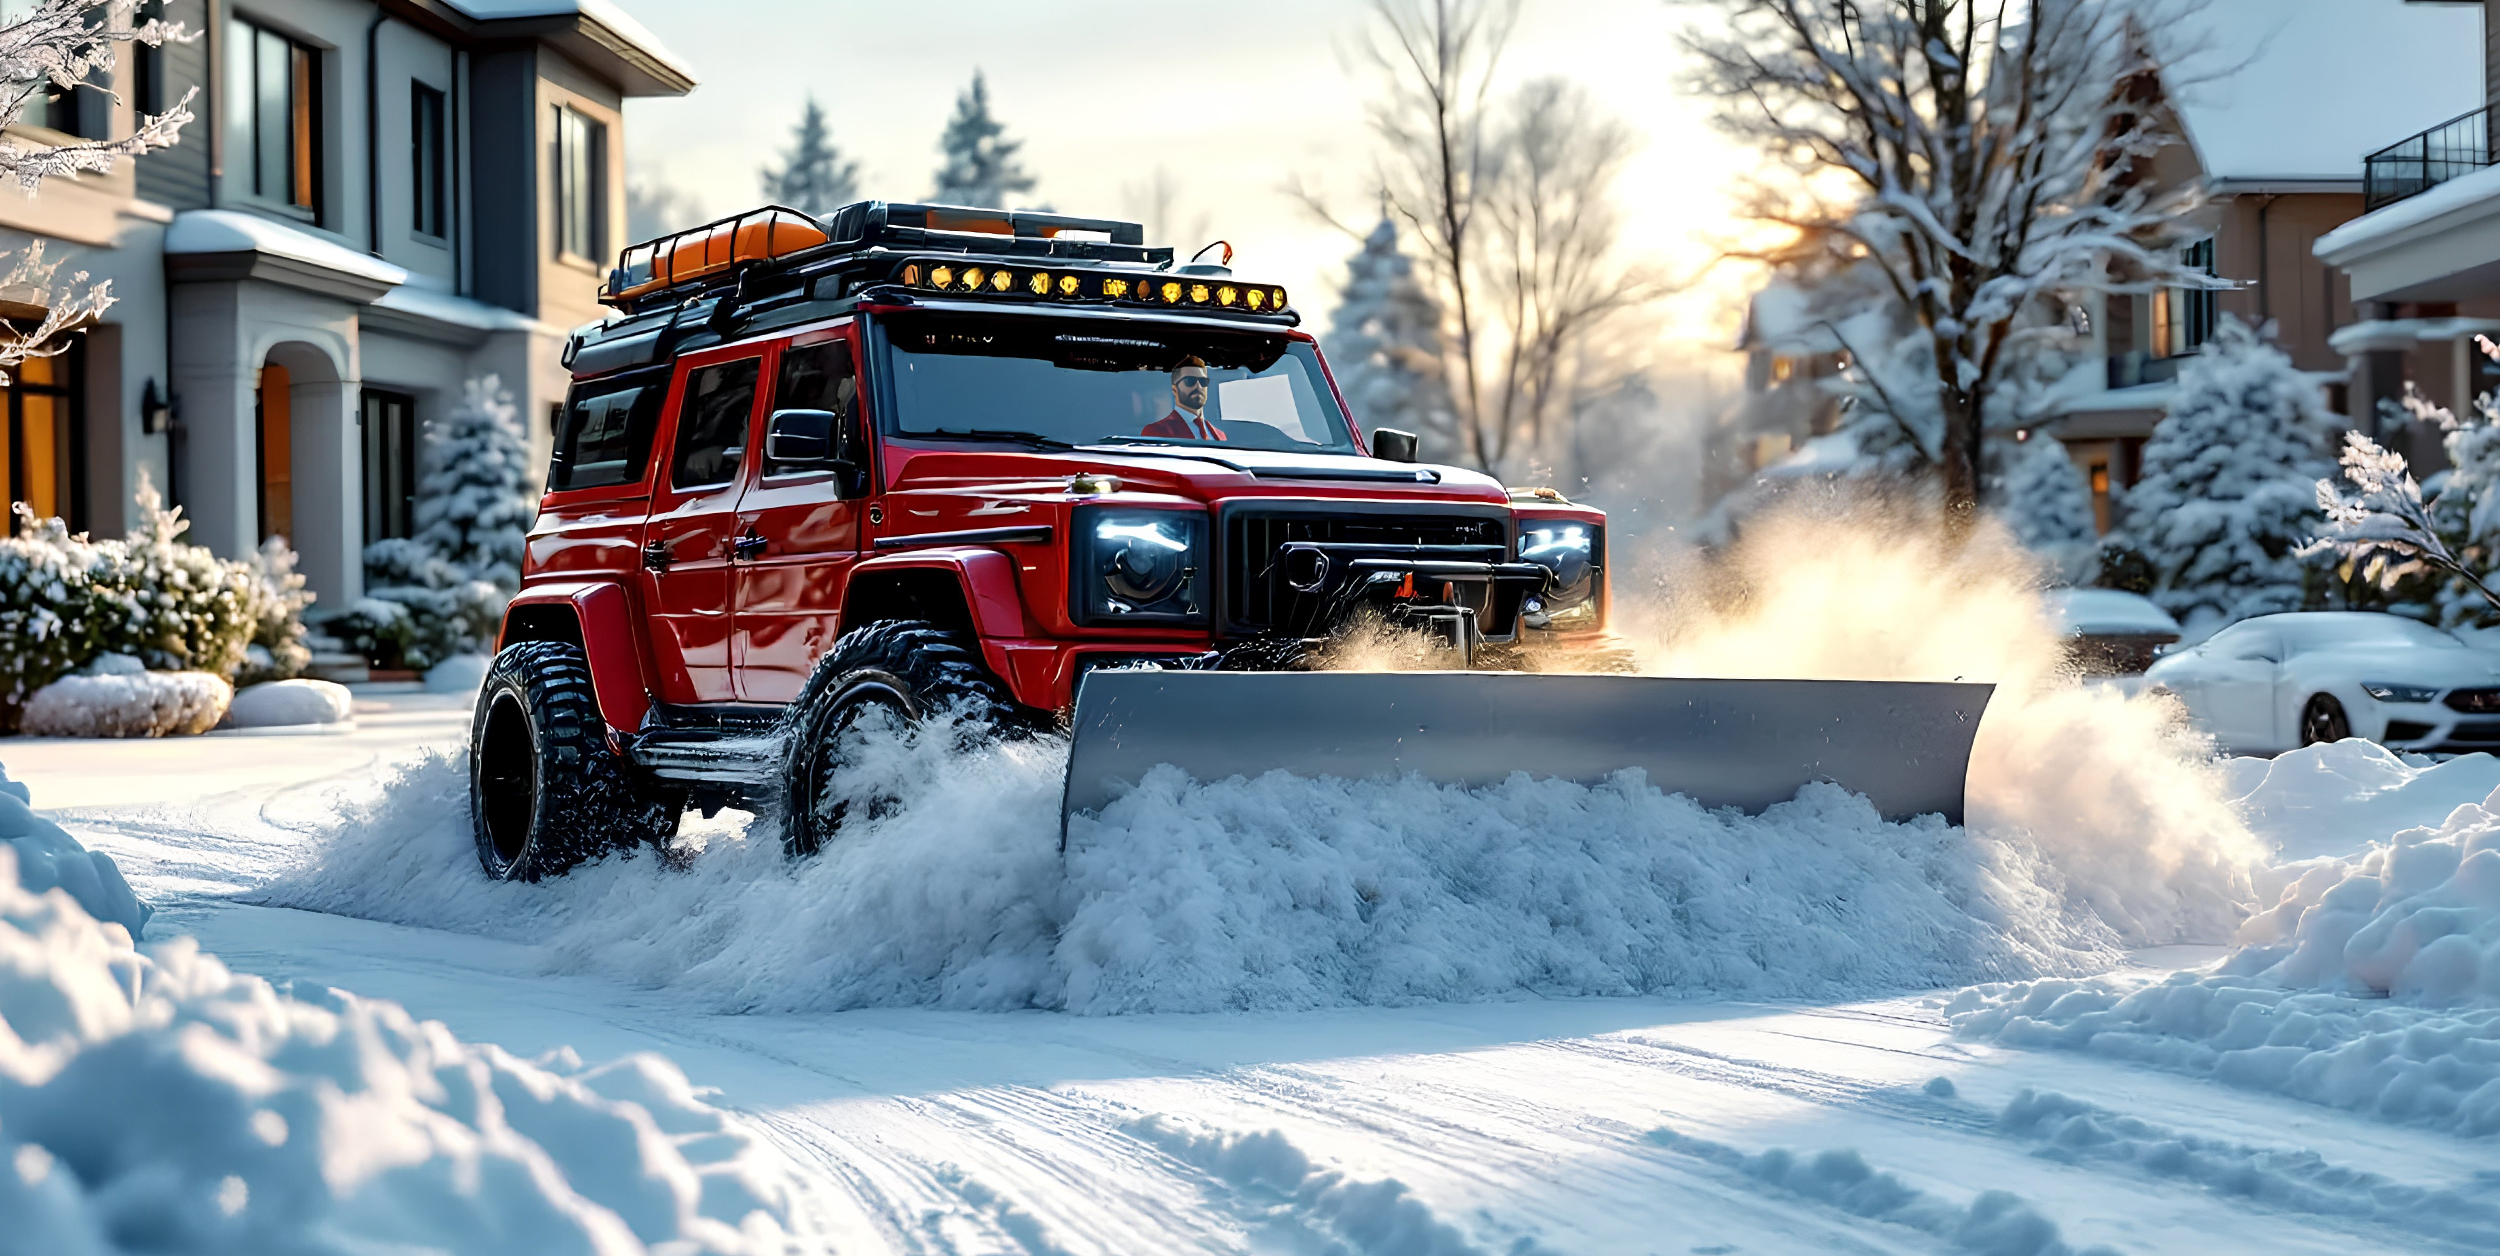
Safeguard your Snow removal business with tailored liability insurance.
Proudly Canadian, protecting Canadian businesses
Save up to 35% on your business insurance
Grab your business insurance quote in moments!
Snow removal insurance: Common questions answered
Snow removal businesses face unique risks every winter, from property damage caused during plowing to slip-and-fall accidents on cleared surfaces. Insurance for snow removal contractors ensures that business owners are protected from costly claims and unforeseen financial losses. Below are some of the most common questions business owners have about snow removal insurance, along with detailed answers.
Snow removal is considered a high-risk industry because contractors work in harsh weather conditions, operate heavy machinery, and are directly responsible for keeping properties safe. Accidents such as damaging a client’s property with equipment or someone slipping on an icy surface can lead to expensive lawsuits. Specialized insurance ensures that these unique risks are covered, protecting both your finances and reputation.
A typical policy may include:
General Liability Insurance (covers third-party injuries and property damage)
Commercial Auto Insurance (for plow trucks and work vehicles)
Contractor’s Equipment Coverage (protects snowblowers, plows, and skid steers)
Workers’ Compensation (covers employee injuries on the job)
This combination ensures you’re covered whether the incident involves property, equipment, employees, or the general public.
Yes, but this is one of the most critical coverages for snow removal contractors. Slip-and-fall accidents are the number one liability risk in this industry. If a client or third party claims you didn’t adequately clear snow or ice, they could sue for medical bills, lost wages, or pain and suffering. Insurance helps cover legal fees, settlements, and damages, ensuring one incident doesn’t bankrupt your business.
The cost depends on factors like:
Business size and annual revenue
Types of contracts (residential, commercial, municipal)
Equipment owned and used
Number of employees
Claims history
On average, small operators may pay a few thousand dollars annually, while larger operations handling municipal contracts could pay significantly more. Insurance is customized to fit the scope and scale of your business.
Not always. If you hire subcontractors, you may need to require them to carry their own insurance and provide proof of coverage. Otherwise, you could be held liable for accidents they cause. Some policies allow you to add subcontractors, but this must be specified. It’s important to clarify this with your broker before contracts begin.
Types of Snow removal businesses that need insurance
- Residential snow removal services
- Commercial snow removal contractors
- Municipal or city snow clearing services
- Driveway and walkway snow removal companies
- Parking lot plowing services
- Sidewalk clearing services
- Salting and de-icing contractors
- Seasonal snow removal subcontractors
- Heavy equipment snow operators (plows, loaders, skid steers)
Our partner brokers work for you
- Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
- We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
- We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Why choose GETRATES?
Why great insurance doesn’t have to cost more
- Our partner brokers work with over 40 trusted insurance providers to offer a wide range of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
- By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
- Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.
Common insurance claim scenarios for Snow removal businesses
Snow removal contractors face frequent and costly risks during winter operations. These scenarios highlight why insurance is critical and how it provides financial protection.
Slip-and-Fall Accidents on Cleared Property
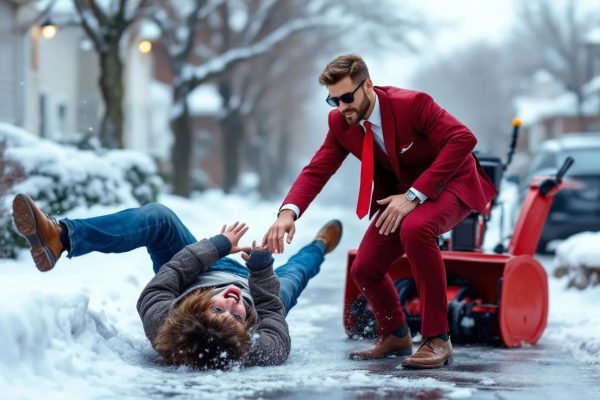
Problem: A client hires you to clear snow and ice, but a passerby slips on a patch of ice that wasn’t fully treated. The injured person sues for medical expenses and lost wages.
How Insurance Helps: General liability insurance covers the legal defense, medical costs, and any settlements, protecting your business from financial devastation.
Property Damage from Snow Removal Equipment
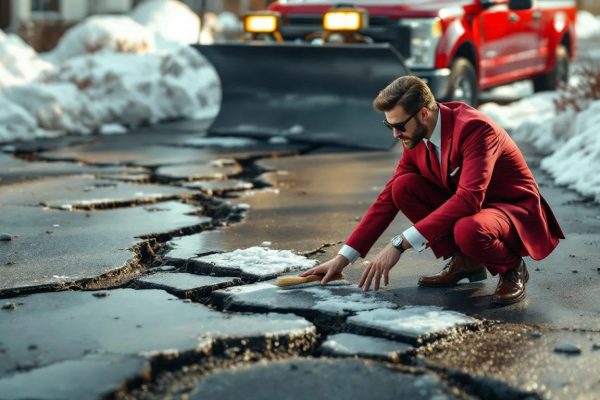
Problem: While plowing a driveway, your truck’s blade digs too deep, leaving visible scratches and cracks on the homeowner’s pavement. The client demands costly repairs or replacement.
How Insurance Helps: Liability insurance covers the cost of repairing or replacing the damaged driveway, ensuring you don’t have to pay out-of-pocket for accidental property damage.
Employee Injury While Operating Equipment
Problem: One of your workers injures their back while shoveling or gets hurt operating a snowblower in icy conditions. Without coverage, medical bills and lost wages fall on your business.
How Insurance Helps: Workers’ compensation insurance covers the employee’s medical expenses, rehabilitation, and lost wages, helping them recover while protecting your business from lawsuits.