Affordable insurance safeguards your Side hustle business and finances.
Proudly Canadian, protecting Canadian businesses
Save up to 35% on your business insurance
Grab your business insurance quote in moments!
Side Hustle insurance: Essential coverage explained
Running a side hustle can be exciting and rewarding, but it also comes with risks—financial, legal, and operational. Side hustle insurance provides protection so that your small business doesn’t end up costing you more than it earns. Below are some of the most common questions about side hustle insurance, with detailed answers to help you understand why this coverage matters.
Yes. Even small-scale businesses can face big risks. For example, if a client gets injured while using your product or service, you could be held liable for damages. Without insurance, you’d have to cover legal fees, settlements, or medical bills on your own. Insurance protects your income and personal savings, ensuring your side hustle remains profitable instead of financially draining.
Common coverages include:
General Liability Insurance (covers accidents, injuries, or property damage claims)
Professional Liability Insurance (covers errors, mistakes, or negligence in services)
Business Property Insurance (covers tools, equipment, and inventory)
Cyber Liability Insurance (protects against online fraud or data breaches)
The right coverage depends on what your side hustle involves, whether it’s online, service-based, or product-focused.
Typically, no. Home and auto insurance policies often exclude business activities. For example, if you’re baking and selling goods from your kitchen and a customer gets food poisoning, your homeowner’s insurance won’t cover it. Likewise, if you’re using your car for deliveries, your personal auto insurance likely won’t protect you in the event of an accident. A separate side hustle policy ensures you’re covered properly.
The cost depends on the type of side hustle, risk level, and coverage limits. Some policies start as low as $20–$40 per month for basic coverage. While that might seem like an added expense, it’s far less than the thousands you could pay out-of-pocket for a single claim or lawsuit. Think of it as a small investment to safeguard your growing business.
Without insurance, you’re personally responsible for any damages, lawsuits, or claims. For example, if a client sues you over professional negligence or someone is injured while using your product, you could face legal costs that wipe out your side hustle earnings—and even affect your personal savings. Insurance provides peace of mind so you can focus on growing your business without fear of losing it all.
Types of Side Hustle businesses that need insurance
- Freelancers (writers, designers, developers)
- Consultants and coaches
- Tutors and educators
- Fitness instructors and personal trainers
- Photographers and videographers
- Artists and makers (crafts, jewelry, art sales)
- Bakers and home-based food businesses
- E-commerce sellers (Etsy, Shopify, Amazon, etc.)
- Delivery drivers and rideshare workers
- Pet sitters, dog walkers, and groomers
- Commercial rental Event planners and coordinatorsproperties
- Musicians and entertainers
- Handyman services
- Cleaning services
- Beauty and wellness professionals (makeup artists, hair stylists, etc.)
Our partner brokers work for you
- Our partner brokers are dedicated to your business's best interests, not those of an insurance company. Our advice is always honest and unbiased, ensuring you get the right coverage for your unique needs without any unnecessary extras.
- We take the stress out of shopping for insurance. Our partner brokers compare quotes from top commercial insurance providers to find you the best possible rate, saving you time and effort while securing excellent coverage.
- We know business insurance can be confusing. That's why our partner brokers take the time to clearly explain your options, helping you understand your policy so you can make a confident choice that fits your business and budget perfectly.
Why choose GETRATES?
Why great insurance doesn’t have to cost more
- Our partner brokers work with over 40 trusted insurance providers to offer a wide range of business coverage options. They compare policies side-by-side to find the protection that best fits your company’s needs and budget.
- By looking at multiple quotes for you, they make sure you get the most cost-effective coverage without giving up any of the protection you need. It’s about finding the right policy at the right price. Our advanced technology makes the process of getting insurance quick and efficient. This keeps our costs down — and those savings go straight back to you.
- Our partner brokers extensive portfolio of commercial clients gives them substantial negotiating power with insurers. They use this advantage to secure exclusive rates and enhanced coverage for your business—often resulting in a better overall value than you can find on your own.
Common insurance claim scenarios for Side Hustle businesses
Running a side hustle comes with unique risks. Whether it’s working with clients, selling products, or providing services, unexpected problems can lead to costly claims. Here are the three most common scenarios and how insurance helps:
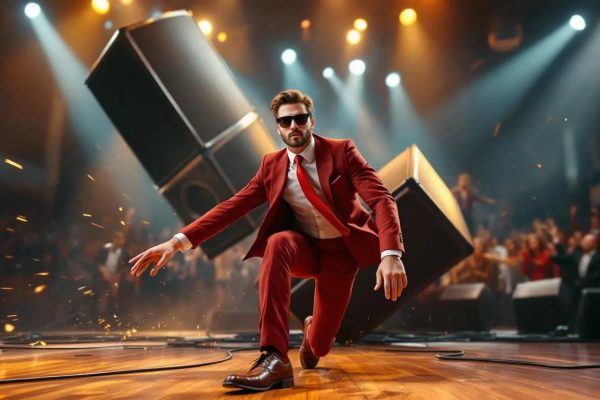
Music Business – Damaged Equipment or Liability at Events
Problem: A musician’s side hustle often involves expensive gear and live performances. If your sound system, instruments, or equipment is damaged in transit — or worse, a speaker topples and injures someone at an event — you could face major financial loss and liability.
How Insurance Helps: Business property insurance covers the cost of repairing or replacing instruments and sound equipment, while liability coverage pays for medical or legal expenses if someone gets hurt during a performance.
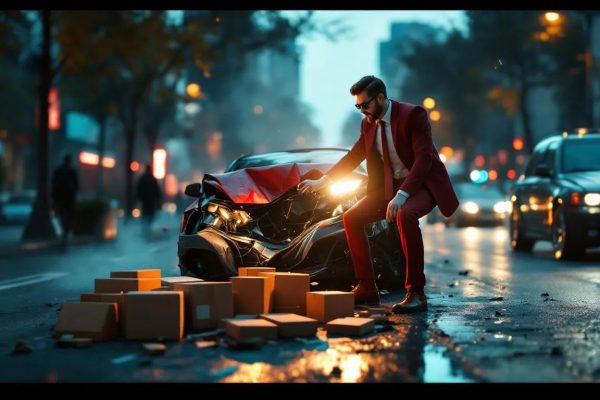
Delivery Services – Auto Accidents and Lost Goods
Problem: If you run a delivery side hustle (food, packages, or courier services), a car accident could damage your vehicle, injure others, or even destroy customer goods. Personal auto insurance often won’t cover accidents while working.
How Insurance Helps: Commercial auto insurance protects you against accident-related costs, including medical bills, repairs, and liability claims. Cargo or goods-in-transit coverage also ensures you’re not paying out of pocket if deliveries are lost or damaged.
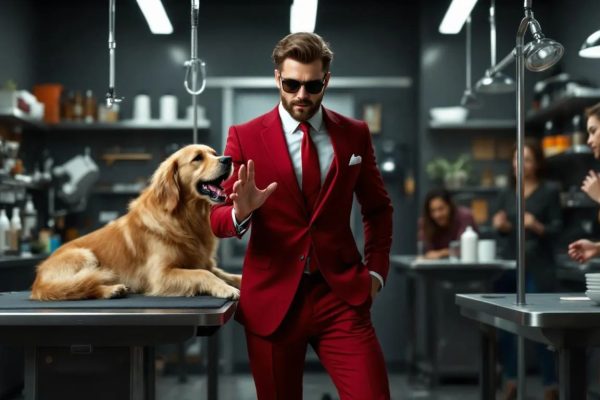
Pet Groomers – Injuries or Property Damage
Problem: Grooming pets at home or on-site carries real risks. A dog might bite you or another customer, or grooming equipment could injure a pet. Even a minor mistake could result in high veterinary bills and a potential lawsuit.
How Insurance Helps: Pet business liability insurance covers injuries to animals and people, as well as damage to a client’s property. It gives peace of mind so you can focus on keeping pets safe and well cared for.